Buy powerscan.eu ?
We are moving the project
powerscan.eu .
Are you interested in purchasing the domain
powerscan.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy powerscan.eu ?
What are the accounting entries in the field of accounting for inventory valuation?
In the field of accounting, inventory valuation involves recording the cost of goods held for sale. The accounting entries for inventory valuation typically include debiting the inventory account to reflect the cost of goods purchased or produced, and crediting the corresponding account such as accounts payable or cash. Additionally, adjustments may be made to account for any changes in the value of inventory, such as writing down inventory to its lower of cost or market value. These adjustments are recorded by debiting cost of goods sold and crediting inventory reserve or loss account. **
How is inventory valuation done in accounting?
Inventory valuation in accounting is done using different methods such as First-In-First-Out (FIFO), Last-In-First-Out (LIFO), and Weighted Average Cost. These methods determine the cost of goods sold and the value of ending inventory. FIFO assumes that the oldest inventory items are sold first, while LIFO assumes that the newest inventory items are sold first. Weighted Average Cost calculates the average cost of all units in inventory. The chosen method can have a significant impact on a company's financial statements and tax liabilities. **


Similar search terms for Accounting
Top-Angebote
Products related to Accounting:
-
DataLogic QuickScan QD2590 2D Barcode Scanner (Scanner Only, Multi-Interface) - BlackDatalogic QuickScan QD2590 (QD2590-BK) handheld 2D area-imager barcode scanner in black. Reads 1D and 2D codes, and the multi-interface electronics support USB, RS-232 and keyboard wedge. Scanner only: the interface cable is not included and is sold separately.96,99 £*Shipping: 0,00 £Secure redirect to the provider
-
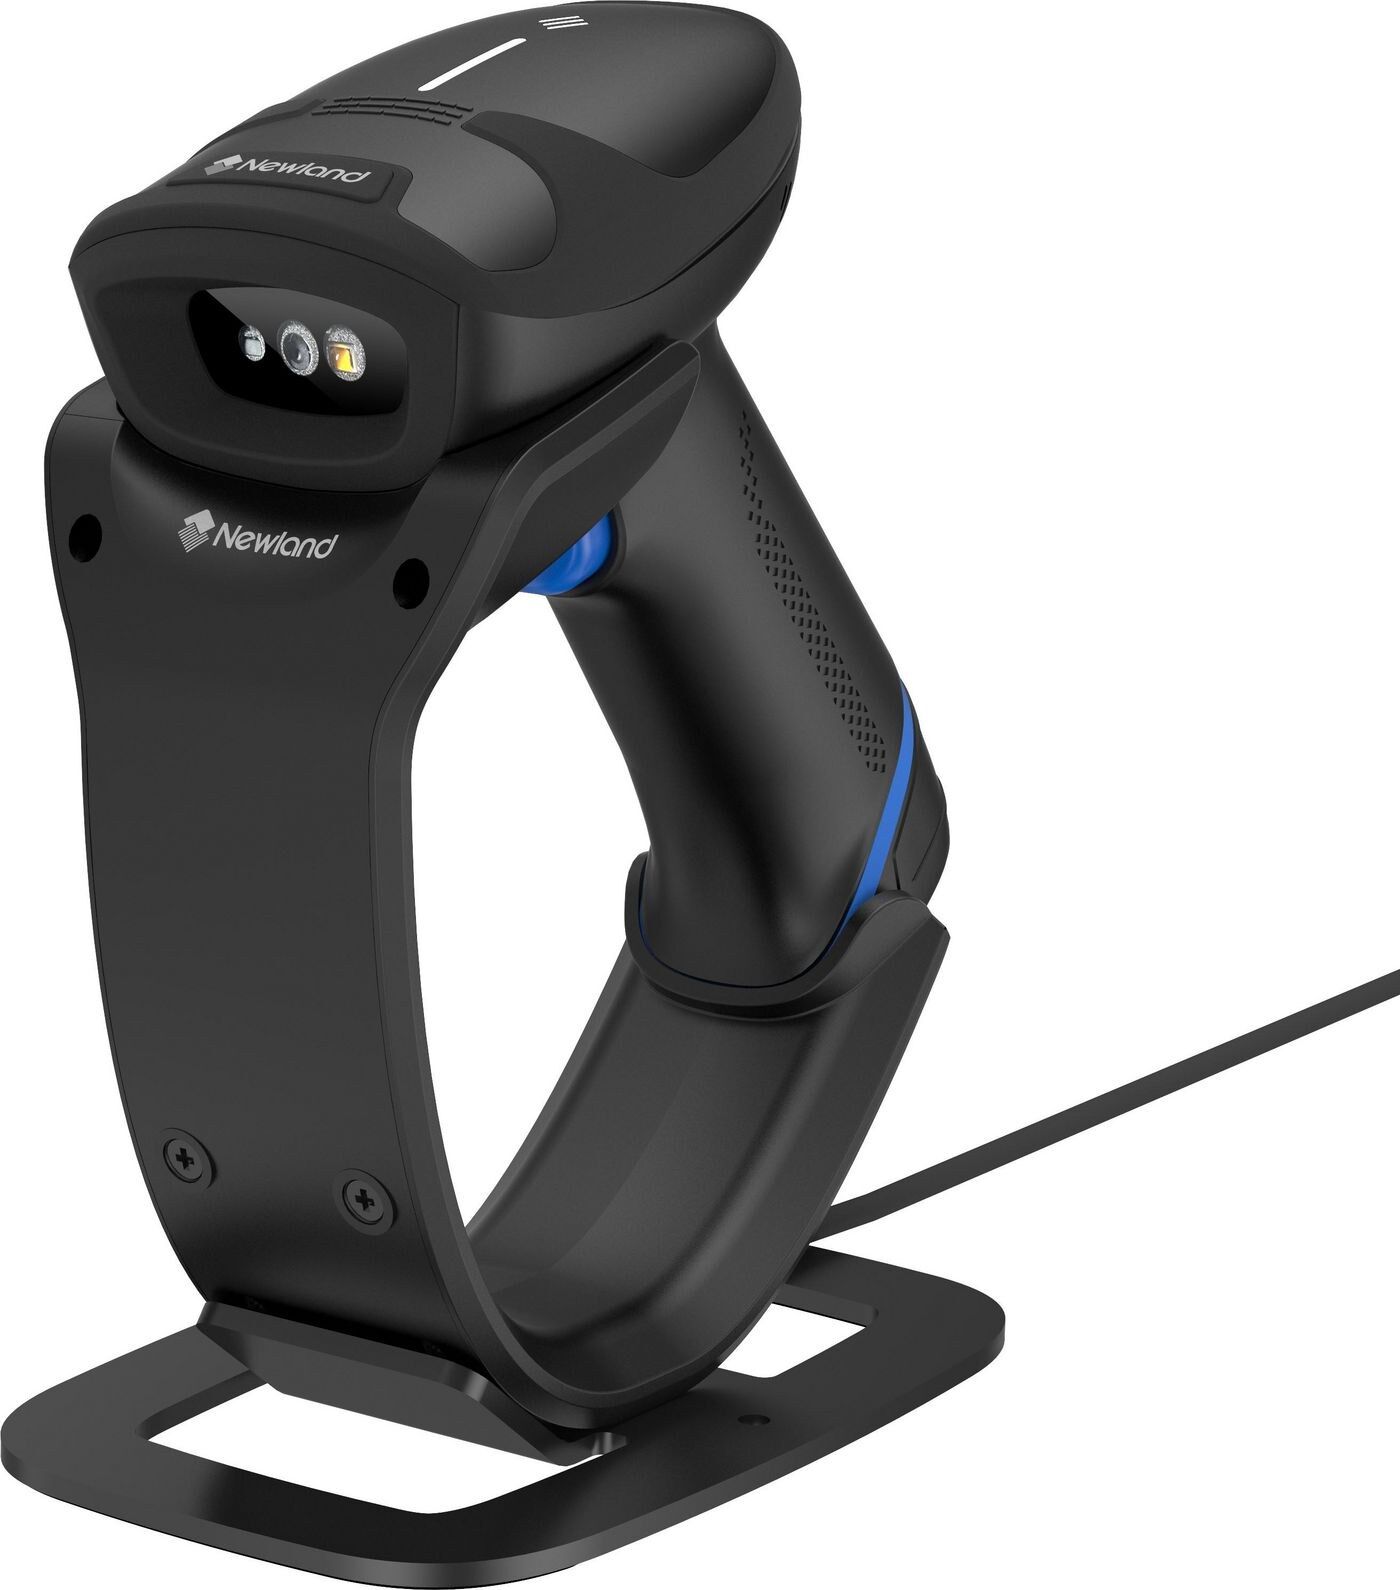
Newland HR33 Marlin 2D Handheld Barcode Scanner - BluetoothNewland HR33 Marlin 2D CMOS megapixel handheld barcode reader, wireless Bluetooth version (NLS-HR3300-BT). Supplied with a communication and charging stand/docking station (NLS-HCD2333) with a 130 cm USB cable fixed to the stand.263,99 £*Shipping: 0,00 £Secure redirect to the provider
-
Opticon OPC-3301i 1D CCD Bluetooth Barcode ScannerOpticon OPC-3301i Bluetooth 1D CCD barcode scanner for linear barcodes. Works with iOS, Android and Windows in HID or SPP mode. Has 1 MB of memory for batch scanning and a 1100 mAh battery. Black, supplied with a wrist strap.213,99 £*Shipping: 0,00 £Secure redirect to the provider
-
Opticon OPI-3301i 2D Bluetooth Barcode Scanner - BlackOpticon OPI-3301i: lightweight wireless handheld 2D CMOS imager barcode scanner with Bluetooth (HID and SPP modes) for Apple, Android and Windows devices. 1 MB memory for batch scanning, 1100 mAh rechargeable battery, wrist strap included. Colour: Black.381,49 £*Shipping: 0,00 £Secure redirect to the provider



-
Does the inventory in accounting not match the target inventory?
If the inventory in accounting does not match the target inventory, it could indicate potential issues such as theft, errors in recording transactions, or discrepancies in the physical counting of inventory. It is important to investigate the root cause of the discrepancy and take corrective actions to reconcile the inventory. This may involve conducting a physical inventory count, reviewing transaction records, and implementing better inventory management practices to prevent future discrepancies. Regular monitoring and reconciliation of inventory can help ensure accurate accounting records and prevent potential losses. **
-
What are the journal entries in accounting for inventory valuation?
The journal entries in accounting for inventory valuation typically involve recording the cost of inventory on the balance sheet. When inventory is purchased, the entry would debit the inventory account and credit the accounts payable or cash account. When inventory is sold, the cost of goods sold account is debited and the inventory account is credited for the cost of the items sold. Additionally, adjustments may be made to the inventory account to reflect changes in the value of inventory, such as write-downs for obsolete or damaged goods. **
-
What are the accounting terms of cost accounting?
Cost accounting involves several key terms, including direct costs, indirect costs, fixed costs, variable costs, and overhead. Direct costs are expenses directly tied to the production of a specific product or service, while indirect costs are not directly tied to a specific product or service. Fixed costs remain constant regardless of production levels, while variable costs fluctuate with production levels. Overhead includes all indirect costs incurred in the production process, such as rent, utilities, and administrative expenses. Understanding and accurately tracking these cost accounting terms is essential for businesses to effectively manage their expenses and make informed financial decisions. **
-
What is a cost center accounting form in accounting?
A cost center accounting form is a document used to track and record the expenses incurred by a specific department or cost center within an organization. It helps in monitoring and controlling costs associated with a particular area of the business. The form typically includes details such as the date of the expense, description of the cost, amount spent, and the cost center to which the expense is allocated. By using cost center accounting forms, businesses can analyze the financial performance of each department and make informed decisions to improve efficiency and profitability. **

What is a cost center accounting sheet in accounting?
A cost center accounting sheet is a document that tracks and records all the costs associated with a specific department or division within a company. It helps management analyze and monitor the expenses incurred by each cost center, allowing for better decision-making and cost control. The sheet typically includes details such as labor costs, overhead expenses, and any other costs directly related to the operations of the cost center. By using this accounting tool, companies can accurately allocate costs, assess performance, and improve efficiency within their organization. **
What is accounting?
Accounting is the process of recording, summarizing, analyzing, and reporting financial transactions of a business or organization. It involves the systematic and detailed recording of financial activities to provide accurate and timely information for decision-making purposes. Accounting helps in tracking the financial health of a business, ensuring compliance with regulations, and providing insights for strategic planning. Overall, accounting plays a crucial role in helping businesses manage their finances effectively and make informed decisions. **
Top-Angebote
Products related to Accounting:
-
Zebra DS2208-SR 2D Barcode Scanner - Black, Scanner Only (No Cable)Zebra DS2208-SR corded handheld 1D/2D barcode scanner, standard range, black. Multi-interface (USB, RS-232, RS-485, keyboard wedge). Reads 1D and 2D codes (QR, Data Matrix, PDF417, UPC/EAN, Code 128 and more) from paper labels and phone screens. Scanner only - cable and stand sold separately.111,99 £*Shipping: 0,00 £Secure redirect to the provider
-
DataLogic QuickScan QD2590 2D Barcode Scanner (Scanner Only, Multi-Interface) - BlackDatalogic QuickScan QD2590 (QD2590-BK) handheld 2D area-imager barcode scanner in black. Reads 1D and 2D codes, and the multi-interface electronics support USB, RS-232 and keyboard wedge. Scanner only: the interface cable is not included and is sold separately.96,99 £*Shipping: 0,00 £Secure redirect to the provider
-
Newland HR33 Marlin 2D Handheld Barcode Scanner - BluetoothNewland HR33 Marlin 2D CMOS megapixel handheld barcode reader, wireless Bluetooth version (NLS-HR3300-BT). Supplied with a communication and charging stand/docking station (NLS-HCD2333) with a 130 cm USB cable fixed to the stand.263,99 £*Shipping: 0,00 £Secure redirect to the provider
-
What are the accounting entries in the field of accounting for inventory valuation?
In the field of accounting, inventory valuation involves recording the cost of goods held for sale. The accounting entries for inventory valuation typically include debiting the inventory account to reflect the cost of goods purchased or produced, and crediting the corresponding account such as accounts payable or cash. Additionally, adjustments may be made to account for any changes in the value of inventory, such as writing down inventory to its lower of cost or market value. These adjustments are recorded by debiting cost of goods sold and crediting inventory reserve or loss account. **
-
How is inventory valuation done in accounting?
Inventory valuation in accounting is done using different methods such as First-In-First-Out (FIFO), Last-In-First-Out (LIFO), and Weighted Average Cost. These methods determine the cost of goods sold and the value of ending inventory. FIFO assumes that the oldest inventory items are sold first, while LIFO assumes that the newest inventory items are sold first. Weighted Average Cost calculates the average cost of all units in inventory. The chosen method can have a significant impact on a company's financial statements and tax liabilities. **
-
Does the inventory in accounting not match the target inventory?
If the inventory in accounting does not match the target inventory, it could indicate potential issues such as theft, errors in recording transactions, or discrepancies in the physical counting of inventory. It is important to investigate the root cause of the discrepancy and take corrective actions to reconcile the inventory. This may involve conducting a physical inventory count, reviewing transaction records, and implementing better inventory management practices to prevent future discrepancies. Regular monitoring and reconciliation of inventory can help ensure accurate accounting records and prevent potential losses. **
-
What are the journal entries in accounting for inventory valuation?
The journal entries in accounting for inventory valuation typically involve recording the cost of inventory on the balance sheet. When inventory is purchased, the entry would debit the inventory account and credit the accounts payable or cash account. When inventory is sold, the cost of goods sold account is debited and the inventory account is credited for the cost of the items sold. Additionally, adjustments may be made to the inventory account to reflect changes in the value of inventory, such as write-downs for obsolete or damaged goods. **
Similar search terms for Accounting
-
Opticon OPC-3301i 1D CCD Bluetooth Barcode ScannerOpticon OPC-3301i Bluetooth 1D CCD barcode scanner for linear barcodes. Works with iOS, Android and Windows in HID or SPP mode. Has 1 MB of memory for batch scanning and a 1100 mAh battery. Black, supplied with a wrist strap.213,99 £*Shipping: 0,00 £Secure redirect to the provider
-
Opticon OPI-3301i 2D Bluetooth Barcode Scanner - BlackOpticon OPI-3301i: lightweight wireless handheld 2D CMOS imager barcode scanner with Bluetooth (HID and SPP modes) for Apple, Android and Windows devices. 1 MB memory for batch scanning, 1100 mAh rechargeable battery, wrist strap included. Colour: Black.381,49 £*Shipping: 0,00 £Secure redirect to the provider
-
DataLogic Gryphon I GD4290 1D Linear Imager Barcode Scanner - Multi-Interface, White (Scanner Only)Datalogic Gryphon I GD4290 handheld 1D linear imager barcode scanner for general-purpose scanning. Multi-interface model in white. Supplied as the scanner only - the interface cable is not included and must be ordered separately.91,99 £*Shipping: 0,00 £Secure redirect to the provider
-
What are the accounting terms of cost accounting?
Cost accounting involves several key terms, including direct costs, indirect costs, fixed costs, variable costs, and overhead. Direct costs are expenses directly tied to the production of a specific product or service, while indirect costs are not directly tied to a specific product or service. Fixed costs remain constant regardless of production levels, while variable costs fluctuate with production levels. Overhead includes all indirect costs incurred in the production process, such as rent, utilities, and administrative expenses. Understanding and accurately tracking these cost accounting terms is essential for businesses to effectively manage their expenses and make informed financial decisions. **
-
What is a cost center accounting form in accounting?
A cost center accounting form is a document used to track and record the expenses incurred by a specific department or cost center within an organization. It helps in monitoring and controlling costs associated with a particular area of the business. The form typically includes details such as the date of the expense, description of the cost, amount spent, and the cost center to which the expense is allocated. By using cost center accounting forms, businesses can analyze the financial performance of each department and make informed decisions to improve efficiency and profitability. **
-
What is a cost center accounting sheet in accounting?
A cost center accounting sheet is a document that tracks and records all the costs associated with a specific department or division within a company. It helps management analyze and monitor the expenses incurred by each cost center, allowing for better decision-making and cost control. The sheet typically includes details such as labor costs, overhead expenses, and any other costs directly related to the operations of the cost center. By using this accounting tool, companies can accurately allocate costs, assess performance, and improve efficiency within their organization. **
-
What is accounting?
Accounting is the process of recording, summarizing, analyzing, and reporting financial transactions of a business or organization. It involves the systematic and detailed recording of financial activities to provide accurate and timely information for decision-making purposes. Accounting helps in tracking the financial health of a business, ensuring compliance with regulations, and providing insights for strategic planning. Overall, accounting plays a crucial role in helping businesses manage their finances effectively and make informed decisions. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.